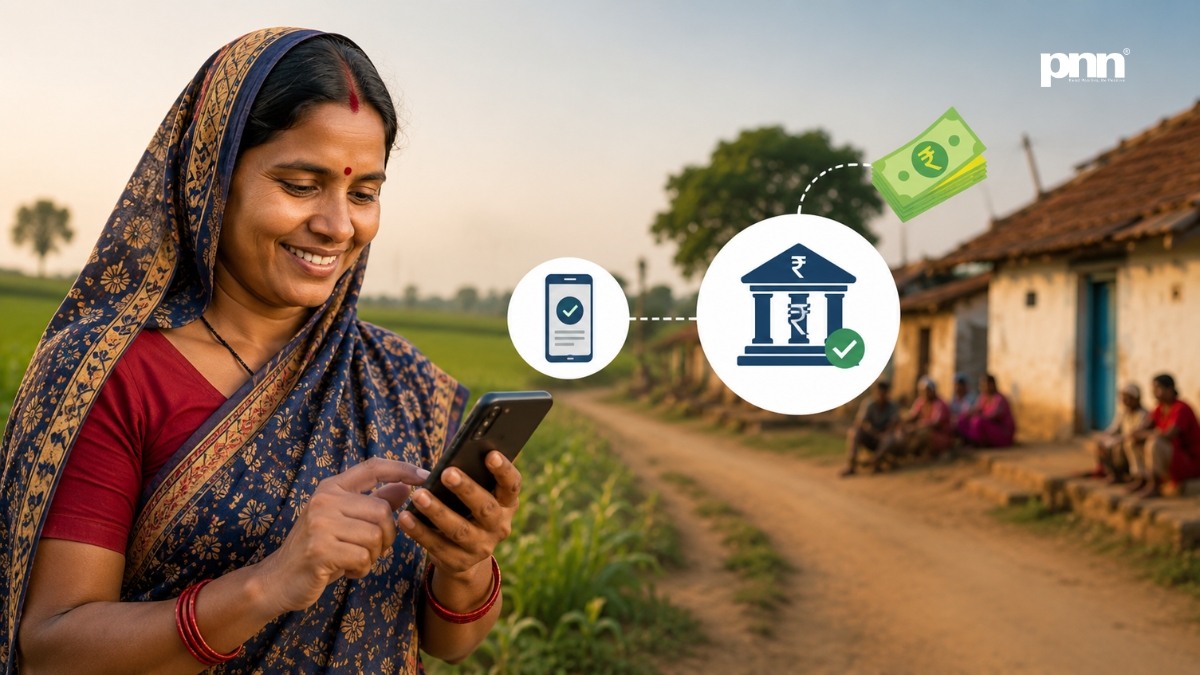
Mumbai (Maharashtra) [India], July 30: Picture this: somewhere in a village, a farmer, a tailor, or a small shopkeeper grabs their phone — nothing fancy, just a basic one — pokes a few buttons, and boom. Money pops into their account. No need to hunt for a bank branch, fill out stacks of paperwork, or stand sweating in a long queue. Instead, all it takes is a phone, a signal, and a credit score that gets built quietly in the background.
That’s not just some tech fantasy. It’s everyday life now for millions in rural Kenya, India, Bangladesh, and the Philippines.
The Problem Mobile Loans Are Solving
So, what’s actually changing? For years, getting credit in rural areas meant trekking to the nearest bank, sometimes hours away, or dealing with local moneylenders who charged brutal interest rates. Banks couldn’t bother setting up branches in tiny villages, so folks were stuck borrowing at 5-10% interest per month from whoever was convenient.
But mobile loans flipped it completely. Now, the bank’s in your pocket.
Kenya’s M-Shwari: The Model Everyone Studies
Take Kenya. M-Pesa launched back in 2007 so people could send cash by text. Then came M-Shwari — a real game-changer. Safaricom and Commercial Bank of Africa cooked up a way for people to borrow and save, all within that phone wallet. No loan officer, no collateral, no branch visits. The system just looks at your phone wallet behavior — topping up airtime, saving regularly, paying back micro-loans — and decides, in seconds, if you can borrow. Usually, we’re talking a couple thousand shillings, and the money arrives instantly.
Since then, loads of similar products — KCB M-Pesa, Fuliza, Tala — popped up across East Africa. Suddenly, people with zero formal credit history could borrow small amounts just to keep their shops running or handle a sudden emergency.
India’s Push Through the “JAM” Trinity
India took a different approach — but just as effective. Instead of depending on one company, the government set up the basics so dozens of companies could build on top. That’s the JAM trinity: a basic bank account for everyone, a biometric ID, and a mobile number. Once this plumbing was in place, UPI came in, letting people make instant transfers from any phone, even simple ones, through UPI 123Pay.
Banks and fintechs piled on, offering “instant personal loans,” approved by what you do digitally — not by a stack of documents. So, a vegetable vendor in a remote village can get a working-capital loan just because she has a digital footprint, even if she’s never set foot in a bank.
Self-help groups changed things, too. These rural women’s collectives often use a single shared smartphone to manage savings and loan requests, cutting out pesky middlemen.
Bangladesh and the Philippines Follow Similar Paths
Bangladesh grabbed the same blueprint. bKash — backed by BRAC Bank — turned mobile wallets into channels for loans to garment workers and rural families who never touched a bank account before. Over in the Philippines, GCash lets folks build a transaction history through simple bill payments, and that record turns into the basis for small loans right from inside the app.
The pattern’s clear: the phone stops being just a payment tool. It quietly becomes your financial identity.
Why This Actually Works
So, why does it work? There are three big reasons:
- Data now stands in for paperwork. Instead of asking for salary slips or property papers, lenders just peek at your transaction history — your top-ups, bill payments, savings habits — and figure out if you’re likely to repay.
- The cost to reach people plummets. There’s no building a branch, no hiring staff in remote corners. Your phone gets you the loan, whether you’re 300 kilometers from the nearest bank or sitting in a city.
- Trust grows bit by bit. Loans start small — maybe a few thousand rupees or shillings. If you pay back on time, they’ll bump up your limit. So first-time borrowers get a chance to build a track record, never filling out a single form.
The Catches Nobody Should Ignore
Still, it’s not a magic bullet. Interest rates can sting — once you crunch them into annual rates, they’re often high. Not everyone really understands these apps; a GCash study showed a lot of low-income users are still shaky about security, which opens doors for scams and fraud. Blanket coverage isn’t there, either. In parts of India, Bangladesh, and East Africa, lousy network signals mean the poorest households stay locked out.
Another problem: people stacking up loans. Because approval is almost instant, some borrowers juggle multiple loans from different apps, piling up debts they can barely track. Regulators in Kenya and India stepped in, setting rules to prevent lenders from offering too many active loans to one user.
What It Means for a Village
But the change is obvious. A shopkeeper who used to wait weeks for a loan (if they ever got one) can now restock overnight. A farmer buys seeds before the next harvest — no collateral, no hassle. A self-help group dishes out loans to its members in minutes, not days.
Phones haven’t replaced banks, but now they’re the front door. And finally, that door opens all the way down the dusty village road.